The Debate Between Islamic and Traditional Banking
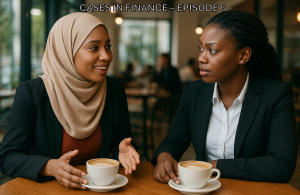
The question sliced through the cafeteria buzz like a sharp knife through ripe mango. The cafeteria buzzed with laughter, clinking cups, and the low hum of MBA students exchanging big ideas. At a corner table sat Jamila and Naa Lamley, friendship forged in the halls of Wesley Girls High School, four years as roommates at University of Ghana, Legon, and now a shared MBA pursuit at the University of Ghana Business School.
They had walked different paths since graduation in 2011. Jamila, with her headscarf tied neatly, had gone North to Tamale to build a rice and cattle farm. Naa Kwaley, bold and relentless, had built a small empire retailing premix fuel to fishermen in James Town. Both ventures had survived storms, grown steadily and now stood at a crossroads: expansion. They both needed over GHS500,000 and that is where their harmony ended.
“Jamila,” Naa teased, stirring her cappuccino, “you’re too stubborn.” Traditional banking is straightforward; you borrow, you pay interest, you move on. Why complicate things with all this Islamic Banking talk?”
The Features of Islamic Banking
Jamila smiled. “Because my faith guides my choices. And Islamic Banking isn’t just about religion; it’s about fairness, risk-sharing and building something real.”
She leaned forward, explaining. “In Islamic Banking, Riba, what you call interest is forbidden. Banks can’t simply lend money and collect interest no matter the outcome. Instead, they earn through trade, investment or structured partnerships. It forces both the Bank and the client to focus on creating real value, not just chasing returns.”
She continued, her voice steady. “If I borrow, the bank and I share both profits and losses. That happens through models like Mudarabah, which is profit-sharing, or Musharakah, which is a joint venture. It’s not just me bearing the entire burden if things go wrong. We walk the journey together.”
Jamila’s hands traced small circles on the table as she spoke. “And there’s another thing; every transaction has to be tied to something real, a tangible asset. There’s no such thing as money floating in thin air or bets on speculation. If I’m financing cattle, there has to be cattle. If it’s land, the land has to be there. It keeps the system grounded.”
Finally, her tone softened. “And the investments themselves must be ethical. That means no alcohol, no gambling, no shady or exploitative businesses. Some Islamic banks even set aside a portion of their profits for Zakat; charity to uplift communities. So in a sense, every deal contributes to society, not just shareholders.”
Naa raised an eyebrow, her lips curving into a half-smile. “Sounds noble. But also… complicated.” Jamila laughed lightly. “Yes, the contracts can be tricky. But think about it, whiles traditional banks put all the risk on you, Islamic banks share it. That’s powerful.”
The Differences
They compared notes, like students cramming before a big exam. Jamila leaned closer, her eyes shining as she laid out the contrasts. “First, interest,” she began. “In Islamic banking, it’s completely forbidden. We don’t pay or receive riba. Instead, profits come from trade, leasing, or equity participation. Traditional banks, on the other hand, survive on interest; it’s their lifeblood, their main source of income.”
She paused for a sip of tea before continuing. “Then there’s the question of risk. In my system, both the bank and client share it. If the business succeeds, we both win. If it fails, we both feel the loss. But with your kind of banking, Naa, the borrower bears the whole weight, whether or not the venture works out. And don’t forget assets, Islamic banks only finance when there’s something tangible, something real to tie the money to. Traditional banks can lend freely without such backing.”
Naa tilted her head, listening carefully. Jamila pressed on. “Ethics also draw a line. Islamic finance follows Shariah principles, so funds can’t be invested in alcohol, gambling, or anything considered haram. Conventional banks don’t carry such restrictions beyond the law. And finally, speculation, my system avoids it. Contracts must be clear, transparent and free of uncertainty. But in traditional banking, speculation is allowed, as long as it’s legal.”
Finance Lens
From a financial perspective, the contrast is striking. Islamic banking prohibits interest, enforces risk-sharing, insists on asset-backing, and demands ethical investment. Traditional banking, meanwhile, thrives on interest-based lending, enjoys wider product availability and moves faster. One model emphasizes partnership and real-economy activity, the other prioritizes efficiency and scale. Both approaches can work, but the implications for borrowers and economies are vastly different.
The Merits and Demerits
“See?” Jamila said, tapping the table for emphasis. “Islamic banking is about partnership. Yours is about debt.” She explained that the foundation of Islamic finance rests on shared responsibility; banks and clients working together rather than one party bearing all the risk. Unlike traditional systems where the borrower shoulders the full weight of repayment plus interest, Islamic models distribute both profit and loss. This principle, Jamila stressed, nurtures trust and creates healthier and more sustainable relationships between banks and their clients. Naa chuckled in response, pointing out the imperfections. “And yours has its flaws too. Limited products, high transaction costs, no global standard. Sometimes it feels like profit-sharing is just interest in disguise.”
Jamila nodded, acknowledging the critique but refusing to dismiss the potential. “True,” she admitted, “but Islamic banking has strengths that matter. It encourages real economic activity because every deal must be tied to tangible assets. It reduces reckless speculation, which so often leads to bubbles and crashes. Most importantly, it provides financial inclusion for Muslims who’ve stayed away from conventional banks for religious reasons.” Her voice grew more hopeful as she added, “Imagine what that could do in Ghana; drawing more people into the financial system, channeling idle capital into productive use, and supporting businesses that need real partnerships instead of just debt.”
The Economic Impact
Her eyes lit up as she painted the bigger picture. “Islamic banking can fuel entrepreneurship. Small farmers like me can get capital without drowning in debt. Instead of being trapped by compounding interest, we can build businesses and grow in a way that feels sustainable.”
“It can also broaden the financial base, drawing in people who’ve long stayed away from banks. For many, faith has kept them outside the formal system, but Islamic banking opens a doorway where their values and financial needs align.” “By tying money to assets, Islamic banking stabilizes economies and avoids bubbles. Every transaction is grounded in something real; land, goods, services, which reduces the risks of the kind of financial crises that speculation often creates.”
“It can mobilize dormant capital too. Money that people would have otherwise hidden under pillows for fear of interest can now flow into the economy, creating opportunities instead of sitting idle.” “Even government benefit. With Islamic bonds, known as Sukuk, nations can raise funds to build roads, schools and hospitals to strengthen development without falling into unsustainable debt traps.”
“And beyond the economics, there’s the social side. Zakat, the system of charity built into Islamic finance which helps communities grow by ensuring wealth circulates to those who need it the most.”
Moment of Clarity
For a moment, Naa said nothing. The imagery of fishermen gaining loans through fair risk-sharing, or farmers expanding without crippling debt, lingered in her mind. She had always seen finance as mechanical; numbers in, numbers out. But Jamila’s words reframed it: banking could be a tool for justice, inclusion and shared progress. The debate wasn’t just about contracts. It was about lives.
Finally, Naa smiled. “Maybe… just maybe… Ghana needs both systems. Yours for fairness, mine for speed. Together, they could push us from developing to developed.” Jamila raised her teacup. “Agreed. Two friends, two banks but one goal: growth.” They clinked cups, sealing not just a debate, but a vision of finance as nation-building.
Lessons for Borrowers and Banks
For Borrowers (Entrepreneurs seeking funding):
Traditional loans may be faster and simpler, but they push the entire repayment risk on you, regardless of your business outcome.
Islamic finance eases that burden by sharing risk, though the contracts can be complex and require deeper understanding.
Always seek clarity in terms, whether conventional or Shariah-based to avoid surprises hidden in fine print.
Match the type of financing to your business model; for asset-heavy ventures, Islamic finance may align better, while for quick cash needs, conventional loans might be more practical.
Do not just focus on cost, consider the long-term relationship a financing model fosters. Partnership-based funding can open doors beyond money into mentorship, networks and trust.
For Banks:
Islamic banks must simplify, innovate and standardize products if they want to expand beyond niche customers.
Traditional banks can adopt principles of fairness, transparency and ethical investing to win deeper trust and loyalty.
Both models should embrace financial inclusion, bringing in the unbanked population to widen the economic base.
By sharing lessons across systems, banks can design hybrid products, marrying the efficiency of conventional banking with the ethics of Islamic finance.
Ultimately, both types of banks play a national role: mobilizing capital, fueling entrepreneurship and propelling economies like Ghana’s toward sustainable development.
Discussion Questions
From Jamila and Naa’s debate, what does the contrast between Islamic banking and traditional banking reveal about how risk and responsibility are distributed between banks and borrowers?
In what ways can Islamic banking principles (such as asset-backing and risk-sharing) contribute to financial stability in developing economies like Ghana?
What are the key challenges Islamic banks face in scaling up compared to traditional banks, and how might these challenges be addressed?
How can both banking systems—Islamic and traditional—complement each other to expand financial inclusion and support entrepreneurship?
If you were advising the Ghanaian government, how would you balance promoting traditional banking and Islamic banking to achieve national development goals?


