Baby Boomers who argue borrowers today have it easy compared with the 17.5 per cent interest rates of the early 1990s are overlooking the reality of modern mortgage debt, according to veteran real estate commentator Tom Panos.
While borrowers in the early 1990s faced sky-high interest rates, Panos said mortgage debt now consumes a far greater share of household income, leaving many families struggling with repayments as well as soaring costs for essentials.
Panos said he often hears older Australians dismiss current mortgage stress without appreciating how dramatically mortgage debt has grown.
‘A guy said to me yesterday, “Tom we had 17.5 per cent interest rates, what are these people going on about?”‘ he recounted.
‘I was there, I was in that market and I remember what it felt like.
‘I remember I was just starting out in real estate, forced sales, mortgagee sales, phone calls, pressure on families, businesses going shut. Brutal.
‘But I can tell you what I’m seeing families carrying today, and I can tell you it’s harder than what people think.
‘4.6 per cent on a giant mortgage is more painful.’
Panos said the pain felt by millions of Australians was not the interest rate itself, but the share of household income being swallowed by mortgage repayments.
He said homes in the early 1990s were far cheaper relative to incomes, meaning households carried significantly less debt despite much higher interest rates.
For example in 1990, Sydney’s median house price was about $187,000. A buyer with a 20 per cent deposit would have needed a mortgage of about $150,000. Even with interest rates around 17 per cent, the interest bill was roughly $25,000 a year.
Today, Sydney’s median house price is about $1.7million. An 80 per cent mortgage would be around $1.36million. At a mortgage rate of about 6.4 per cent, the interest bill alone would be around $87,000 a year – showing how today’s much bigger mortgages can hurt even when rates are far lower.
‘The debt loads were lower. The average family home was not carrying a mortgage that is eight or nine times their household income,’ he said.
Australians are drowning in debt, with households owing the equivalent of 178 per cent of their annual disposable income in June 2026, among the highest levels since records began in 1977.
Panos said today’s borrowers were also being squeezed by rising prices for almost everything, from petrol, groceries and electricity to school fees.
‘There’s no breathing room and unlike the late 80s and 90s, which was a sharp, brutal period, households today have been carrying this pressure for a few years,’ he said.
‘Yesterday was another turn of the screws. The RBA says it’s fighting inflation, fair enough, inflation hurts everyone. But the bill is landing on mortgage holders, small business owners and young people.
‘The people with cash get higher interest, the people with debt, they’re getting smashed.’
‘This is not a competition about who had it tougher, it’s about recognising the reality of today. The mortgage is so much bigger, and that’s why the pain is so much deeper.’
Panos’ comments came as Reserve Bank governor Michele Bullock signalled rates may need to remain higher for longer as the central bank continues its fight against inflation.
Bullock warned on Tuesday that a recession may be the price of crushing inflation, as borrowers were slugged with a fourth rate rise this year that lifted the cash rate to a 15-year high.
The last time Australia was in a deep recession was in 1991, famously termed ‘the recession we had to have’ by then-treasurer Paul Keating.
Financial markets are increasingly betting on another hike by Christmas, which would take the cash rate to an 18-year high of 4.85 per cent and send variable mortgage rates above 7 per cent for the first time since the global financial crisis in 2008.
‘Every household has seen how the price of everything has gone up in recent years,’ Bullock said after the unanimous decision was announced on Tuesday afternoon.
‘Pay packets don’t go as far as they used to, and that’s why we need to stop this high inflation.
‘The board will raise interest rates again if that’s what’s needed to bring inflation down.’
Bullock acknowledged many mortgage holders failed to grasp why raising interest rates was necessary.
‘If we don’t address this, inflation will get worse and interest rates will have to be higher and the economy in a worse position,’ she said.
‘Ultimately, in the long run, hopefully in those couple of years when we get inflation back down, this will all have been worth it.’
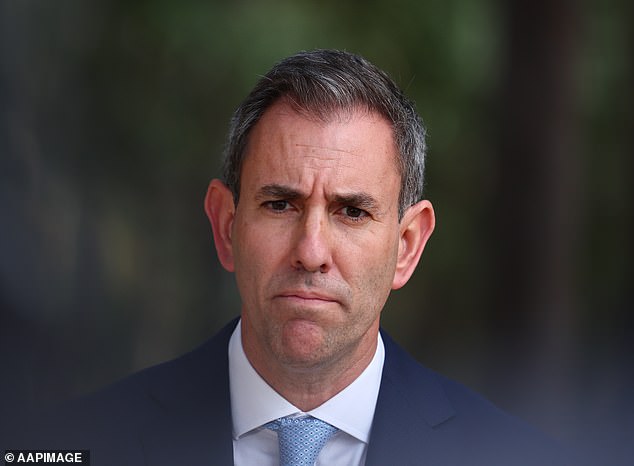
Meanwhile, Treasurer Jim Chalmers handballed some of the blame for the latest rate hike to US President Donald Trump.
‘The war in the Middle East is pushing up inflation and interest rates all around the world but that doesn’t make it any easier for Australians,’ he said.
‘Australian workers didn’t choose this war, but they are paying a hefty price for it.’
AMP chief economist Shane Oliver said the latest hike means roughly an extra $110 a month in mortgage interest payments for those with an average $700,000 mortgage, and a total increase of $440 a month since January, or $5,300 a year.
‘Fortunately, increased competition and discounting means actual mortgage rates are yet to surpass their 2023 high, but they are getting close,’ he said.
‘Inflation has been above target for five of the last six years including this year so the RBA had to hike to preserve its credibility.
‘Of course, the RBA would never put it quite like that.’
Oliver said Bullock had reiterated that excess demand in the economy has to slow to get inflation down sustainably.
‘Put simply, higher than expected inflation for July and ongoing capacity constraints in the economy along with a renewed surge in global energy prices and the data centre boom adding to demand suggested it will take even longer to get inflation back to target than the end of next year,’ he said.
Oliver said the money market is signalling another hike by February and 70 per cent probability of yet another hike by June next year.
Updated inflation data for August will be released by the Australian Bureau of Statistics on Wednesday, just a day after the central bank’s decision to hike the cash rate.

Related posts:
Film depicting first lady’s shooting sparks historical distortion controversy
Ambassador Roh Jae-hun optimistic on full-scale Korea-China cultural revival
Majorca vs Menorca vs Ibiza: Which of Spain’s Balearic Islands should you visit?
Hungary’s reckoning with Orban’s corrupt system picks up speed with high-profile arrests